October 5, 2026
Short answer: Every buy-before-you-sell program helps you shop for your next home first. The differences are what come after: how the cost adds up, what happens if your home doesn’t sell, and who keeps the upside. The Knock Bridge Loan™ charges one flat fee set upfront (not a percentage of your sale), 0% interest for six months, buys your home at a price agreed upfront if it doesn’t sell in 180 days,* and lets you keep any upside — all while you keep your own agent and lender.
Comparison reflects publicly available information about other buy-before-you-sell programs as of October 2026. Terms differ by program, market, and borrower, and individual programs may not have every feature described. This article reflects Knock’s perspective.
Why the programs look alike — and where they actually differ
At first glance, buy-before-you-sell programs all promise the same thing: make a strong, non-contingent offer on your next home before your current one sells. That part is table stakes. Where they diverge is in the fine print — the parts that decide what the program actually costs you and how much risk you carry. Three questions separate them: What’s the fee, and can it change? What happens if your home is slow to sell? And if your home sells for more than expected, who pockets the difference?
How the cost is structured
This is the difference buyers feel most. Many programs charge a fee that’s a percentage of your sale price, which means the cost isn’t fully settled when you sign — a higher sale, or more time on the market, can change what you owe. Some also charge interest that keeps accruing until your home sells.
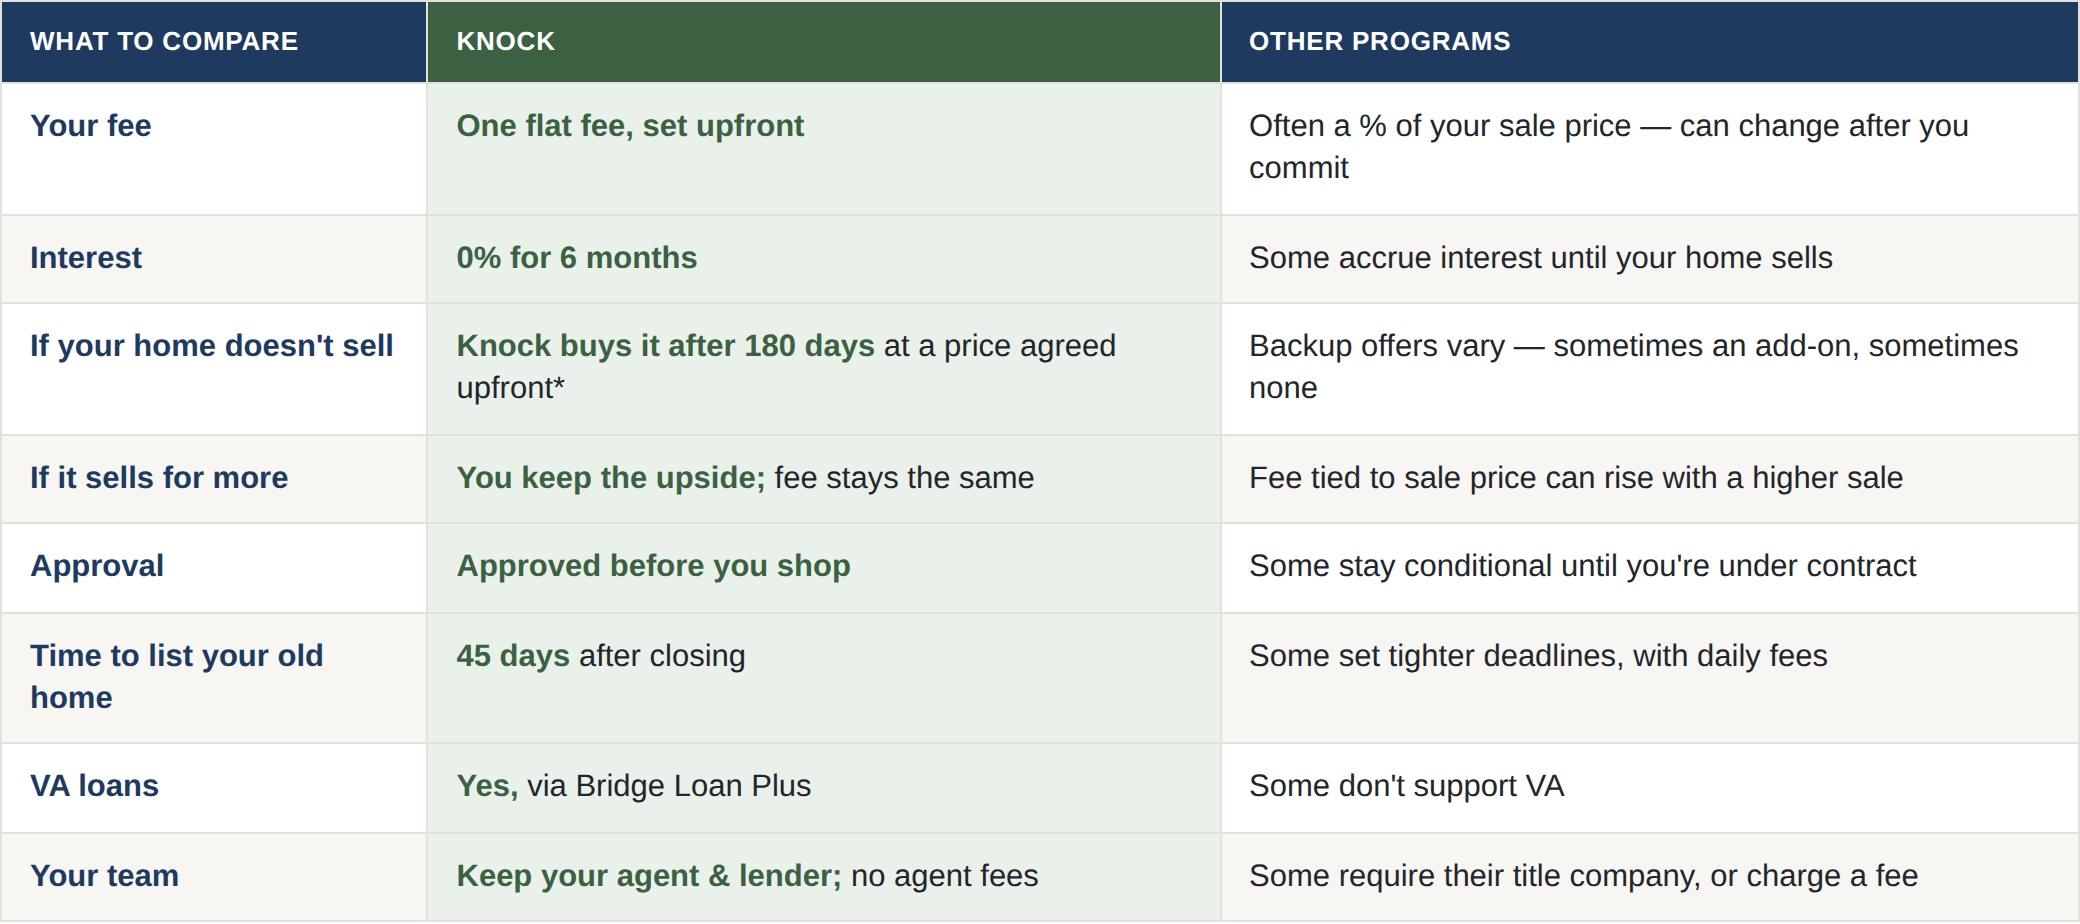
Knock takes the opposite approach: one flat fee, known before you close, plus 0% interest for six months. Your fee doesn’t grow with your sale price or the number of days your home sits on the market. If you want to see how that pencils out, here’s what a Knock Bridge Loan costs.
What happens if your home doesn’t sell
A guaranteed backup offer is the safety net that makes buying first feel safe. But backup offers vary a lot: some programs treat it as an add-on, and some don’t offer one at all. With Knock, if your home hasn’t sold after 180 days, Knock buys it at a price agreed upfront* — and if it sells for more on the open market, you keep the upside and your fee stays the same. Here’s more on what happens if your old house doesn’t sell.
The details that quietly matter
Beyond cost and the backstop, a handful of program details can make a real difference:
Approval timing. Knock approves you before you shop, so you know your budget upfront. Some programs stay conditional until after you’re under contract, pending inspection.
Time to list your old home. Knock gives you 45 days after closing on the new home to list your old one. Some programs set tighter deadlines, with daily fees if you miss them.
VA loans. Knock supports VA financing through Bridge Loan Plus, which also removes your current mortgage from your debt-to-income ratio. Some programs don’t support VA at all.
Your team. Knock lets you keep your own agent and lender, with no fees to agents. Some programs require their own title company or charge a fee if you use yours.
Knock vs. other buy-before-you-sell programs
Frequently asked questions
What’s the biggest difference between Knock and other buy-before-you-sell programs? Cost structure and certainty. Knock charges one flat fee set before you close with 0% interest for six months, while many programs charge a percentage of your sale price that can change after you commit.
What happens if my home doesn’t sell? With Knock, if your home hasn’t sold after 180 days, Knock buys it at a price agreed upfront* — and if it sells for more on the open market, you keep the difference. See what happens if your old house doesn’t sell.
Can I keep my own agent and lender? Yes. Knock works with your existing agent and lender and charges no fees to agents. Some programs route you through their own title company or network.
Does Knock work with VA loans? Yes — through Bridge Loan Plus, which also removes your current mortgage from your debt-to-income ratio so you can qualify for the new loan.
How is this different from selling first? Selling first usually means moving twice or making an offer that depends on your sale. Buying before you sell lets you make a non-contingent offer, use your equity now, and move once. See the complete guide to buying before you sell.
Want to see how the numbers compare for your home? See if your home qualifies for a Knock Bridge Loan, or compare bridge loan vs. contingency costs.
* The Knock Purchase Offer is a written, non-contingent offer from Knock Property 1, LLC to buy your home at an agreed price. Knock Property 1, LLC — a wholly-owned subsidiary of Knock Lending LLC (NMLS #1958445) — is the entity that makes the Knock Purchase Offer and that would purchase the home. You are not required to use Knock Lending or any Knock affiliate.